Wider Spreads, Solid Credits: A Market for Bond-Pickers
European high-yield spreads have widened to near their highest levels in 12 months. This is a repricing of risk, not a broad-based deterioration in credit quality. The uneven adjustment creates opportunities for selective investors.
Spreads are near the year’s widest
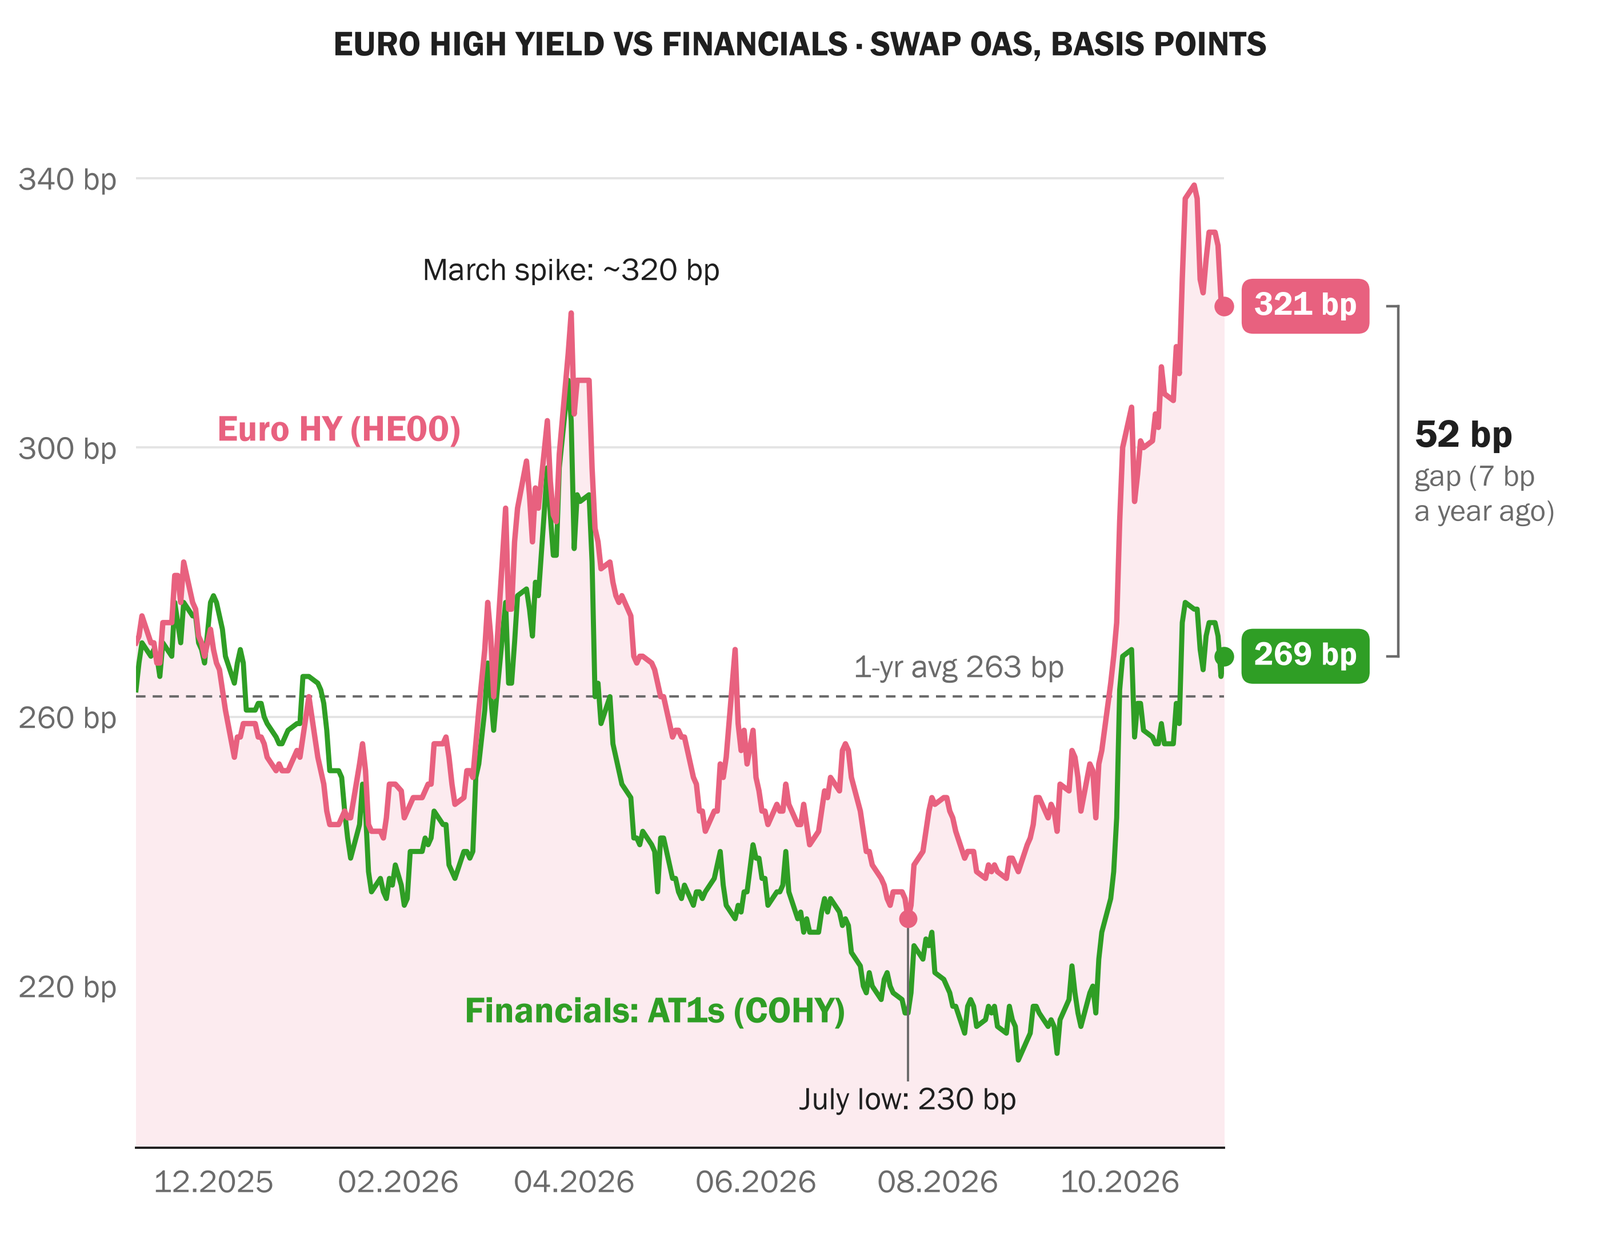
Since mid-September the index has widened by 66bp.
After a spike to about 320bp in March, spreads retraced the whole move to a low of 230bp in July. Then the rally reversed: since mid-September the index has widened by 66bp, to 321bp, just off its 339bp peak of 26 October and nearly 60bp above its one-year average.
Three things drove it: higher rate volatility and real yields, doubts over how the AI build-out will be funded, and firmer energy prices. Weak fund flows against heavy net supply made it worse.
Beneath the index, dispersion is the story
Headline numbers hide a very uneven market.
AT1s normally track Euro HY closely, as they did in March. This time, they moved far less (+5bp vs. +50bp over 12 months), and the gap between AT1 and Euro HY spreads has widened to 52bp, three times its average of 17bp over the past year.
Funding needs have made hyperscalers’ bonds the soft spot of credit: EUR IG hyperscalers’ spreads are 50% wider this year vs. 16% for the rest of the market. In US HY, AI-related spreads widened 50bp in the week to 16 October, vs. 2bp for everything else.
Euro IG telecoms widened more than any sector except autos over the past month. Dispersion within TMT is wide: IG incumbents remain resilient, with free cash flow set to improve as fibre roll-outs near completion, while in HY high leverage and thin margins leave little room for error. The SpaceX spectrum deal also revived the threat to US telcos.
The OAT–Bund spread has widened to around 165bp from 70bp at the start of the year, back to eurozone-crisis levels, on the deficit, energy prices and the 2027 election. Corporates have underperformed their peers, but comparatively less: about 50% of French high-grade corporate bonds (€215bn) now yield less than the OAT, vs. circa 15% one year ago.
Fundamentals have not weakened
Corporates and banks alike are showing solid fundamentals.
Data shows companies and banks are in better shape than in recent years. Leverage is lower, margins are at the top of their post-2008 range. Banks hold more capital and record higher earnings. What has changed is the price investors demand, not the quality of what they own.
The key metric we watch closely is the interest burden. Refinancing has pushed maturities out, but at a higher cost, so we assess each issuer after its refinancing, not before.

What has changed is the price investors demand, not the quality of what they own.
Our stance: be selective, name by name
Dispersion at this level rewards bottom-up work.
When the index widens by 50bp and financials by 5bp, owning the market is a blunt tool. Dispersion of this size rewards bottom-up work twice: by avoiding the credits that reprice, and by buying sound ones that widened only in sympathy with their sector or country.
The sell-off is creating that second opportunity. For example, some good issuers across sectors now trade at levels that, in our view, overstate their risk.
We have no crystal ball on market timing, and risk drivers are present. But opportunities are emerging selectively. A cautious portfolio positioning, adding risk selectively, remains the best strategy in such market conditions.
Past performance is not a reliable indicator of future results.

Past performance is not a reliable indicator of future results.
Two recent positions
Strata · In practice.
Funding Lone Star’s €3.4bn purchase of ContiTech, the new €400m 7NC3 secured notes priced at 7.75%, above every direct similarly rated peer we compared, then fell about 3 points after opening. We added to our position. ContiTech is a global leader in engineered rubber: about 70% aftermarket sales, 3.6x net secured leverage and €1.37bn of sponsor equity below the notes with €161m of expected savings in the EBITDA.
A core holding in our portfolio. The €2.5bn acquisition from Sanofi brings in a listed shareholder with 26%, takes over manufacturing sites after supply problems, and sets a fresh 10x valuation. Net leverage is 3.87x, yet the 6.75% 2032s trade at z+330, against z+210–220 for peers at 5.2–5.3x. An upgrade to B+ would, in our view, justify z+220. Risks: portfolio execution, and Sanofi payments (€202m preferred dividend, up to €93m earn-out a year) from 2028.
Image Gallery
Legal Disclaimer
The Strata Credit Fund is a Sub-Fund of RAM (Lux) Tactical Funds II, a Luxembourg SICAV with registered office: 14, Boulevard Royal L-2449 Luxembourg, approved by the CSSF and constituting a UCITS (Directive 2009/65/EC). The sub-fund STRATA CREDIT FUND was created in the RAM (LUX) Tactical Funds II SICAV to receive the PALLADIUM FCP – RAM Mediobanca Strata UCITS Credit Fund sub-fund. The transfer was effective on 30 May 2024.
Please note that the performance shown reflects periods before the Sub-Fund’s transfer and was achieved under different regulatory and operational conditions, which may no longer apply. Notwithstanding this, the performance is based on investment objectives and policies that have not materially changed following the sub-fund's transfer and is attributable to investment objectives, policies, restrictions, and strategies that are compliant with UCITS regulations. The investment management function remains consistent, with no changes to the team responsible for managing the fund after the transfer. Importantly, there has been no material change in the level of fees charged to investors as a result of this transfer. For further information, please refer to the Prospectus.
Please note that the share classes mentioned in this document may not be registered in your country of domicile.
This marketing document is only provided for information purposes to professional clients, and it does not constitute an offer, investment advice or a solicitation to subscribe shares in any jurisdiction where such an offer or solicitation would not be authorised or it would be unlawful. In particular, the Funds are not offered for sale in the United States or its territories and possessions, nor to any US Person (citizens or residents of the United States of America).
This document is confidential and is intended only for the use of the person to whom it was delivered; it may not be reproduced or distributed.
There is no guarantee that the holdings shown will be held in the future. The investment described concerns the acquisition of shares in the Sub-Fund and not in a specific underlying asset.
Past performance is not a guide to current or future results. There is no guarantee to get back the full amount invested. The performance data do not take into account fees and expenses charged on subscription and redemption of shares nor any taxes that may be levied. As a subscription fee calculation example, if an investor invests EUR 1000 in a fund with a subscription fee of 5%, the investor will pay to his financial intermediary EUR 50.00 on the investment amount, resulting with a subscribed amount of EUR 950.00 in fund shares. In addition, potential account keeping costs (by investor’s custodian) may reduce the performance. Some shares in the Sub-Fund apply a performance fee. Leverage intensifies the risk of potential increased losses or returns.
The Management Company may decide to terminate the marketing arrangement in place in any given country in accordance with Article 93a of Directive 2009/65/EC.
Changes in exchange rates may cause the NAV per share in the investor's base currency to fluctuate.
Particular attention is paid to the contents of this document but no guarantee, warranty or representation, express or implied, is given to the accuracy, correctness or completeness thereof.
Prior to any transaction, clients should check whether it is suited to their personal situation, and analyse the specific risks incurred, especially financial, legal and tax risks, and consult professional advisers if necessary.
Please refer to the Key Investor Information Document and prospectus with special attention to the risk warnings before investing. This Sub-Fund is classified as art.8 SFDR. For further information on ESG, please refer to https://www.ram-ai.com/en/regulatory-information and the relevant Sub-Fund webpage, section "Sustainability-related disclosures".
The prospectus, constitutive documents and financial reports are available in English and French while PRIIPs KID are available in the relevant local languages. These documents can be obtained, free of charge, from the SICAVs’ and Management Company’s head office and www.ram-ai.com, its representative and distributor in Switzerland, RAM Active Investments S.A. and the relevant local representatives in the distribution countries.
Issued in Switzerland by RAM Active Investments S.A. which is authorised and regulated in Switzerland by the Swiss Financial Market Supervisory Authority (FINMA). Issued in the European Union and the EEA by the authorised and regulated Management Company, Mediobanca Management Company S.A. 2 Boulevard de la Foire, 1528, Luxembourg, Grand Duchy of Luxembourg.
The source of the above-mentioned information (except if stated otherwise) is RAM Active Investments and the date of reference is the date of this document.
Austrian Investors: on www.ram-ai.com or from Mediobanca Management Company S.A., 2 boulevard de la foire 1528, Grand-Duché de Luxembourg
Finnish, Norwegian and Dutch Investors: on www.ram-ai.com
Belgian Investors: The factsheet is not addressed to Belgian investors. Please consult the relevant factsheet making a request to Mediobanca Management Company S.A., 2 boulevard de la foire 1528, Grand-Duché de Luxembourg or via www.ram-ai.com
German Investors: on www.ram-ai.com or from Mediobanca Management Company S.A., 2 boulevard de la foire 1528, Grand-Duché de Luxembourg
Portuguese Investors: on www.ram-ai.com or from the local Marketing Entity: BEST - Banco Electrónico de Serviço Total, S.A., Praça Marquês de Pombal, 3 - 3º 1250 Lisboa, Portugal
Swedish Investors: on www.ram-ai.com or from the Paying Agent SKANDINAVISKA ENSKILDA BANKEN AB Stjärntorget 4, SE-169 79 Solna, Sweden
Spanish Investors: RAM (LUX) SYSTEMATIC FUND (870), RAM (LUX) TACTICAL FUNDS (1105) and RAM (LUX) TACTICAL FUNDS II (1620); on www.ram-ai.com or from the appointed distributor Allfunds Bank SA Calle Estafela 6, Complejo Plaza de la fuente, Edificio 3, La Moraleja, Spain.
United Kingdom Investors: on www.ram-ai.com or from the local Facilities Agent Société Générale Securities Services Custody London - 12 Primrose Street, London EC2A 2EG
Swiss Investors: The fund’s documents can be obtained, free of charge, from the following website www.ram-ai.com, and the Swiss representative and paying agent Swiss representative: RAM Active Investments S.A. Rue du Rhône 8 1204 Geneva / Swiss paying agent Caceis Bank Montrouge - succursale de Nyon, Route de Signy 35 CH-1260 Nyon.
More News & insights